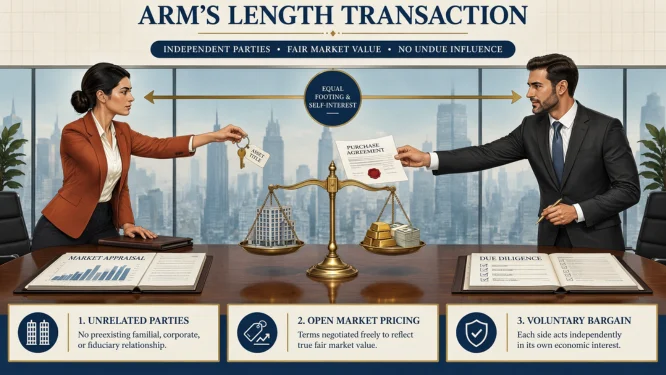
An arm’s length transaction happens when independent parties negotiate for their own interests without improper influence. The price and terms should reflect normal market conditions. This structure helps buyers, sellers, lenders, and tax authorities judge whether a deal reflects fair market value.
The concept appears often in real estate, business sales, taxation, loans, and transactions involving valuable assets. It becomes especially important when the parties have personal or business connections. U.S. authorities may examine those relationships when price or deal terms appear unusual.
Key Facts at a Glance
| Question | Short Answer |
|---|---|
| What does arm’s length mean? | Independent parties negotiate in their separate interests. |
| Must the parties be strangers? | Usually they lack a relationship that can influence the deal. |
| Does it guarantee fair market value? | No, but independent negotiation can provide strong evidence of market value. |
| What is the opposite? | A non-arm’s-length or related-party transaction. |
| Where is the concept important? | Real estate, taxation, business sales, loans, and asset transfers. |
| Can relatives make a valid sale? | Yes, but the deal may receive greater scrutiny. |
| Why do lenders care? | Relationships can affect price, concessions, risk, and property valuation. |
Direct answer: An arm’s-length deal occurs when independent parties negotiate voluntarily and pursue their own economic interests. Neither side controls the other or receives special treatment because of a personal relationship. The resulting price can provide useful evidence of fair market value, although market value still depends on the facts surrounding the transaction.
What Is an Arm’s Length Transaction?
An arm’s-length deal usually involves parties with separate interests and independent bargaining positions. Each side tries to obtain favorable terms. Neither party should be pressured into accepting terms that would not make commercial sense.
Arm’s Length Transaction Cornell Law School’s Legal Information Institute describes arm’s-length dealings as transactions between independent and unrelated parties. The parties generally act voluntarily and in their own interests. Open-market negotiation also helps support the idea that the resulting terms are commercially reasonable.
The idea does not mean both parties must receive identical benefits. A buyer may negotiate a lower price while a seller seeks more money. Their opposing interests are part of what makes the bargaining process useful for determining value.
Why Fair Market Value Matters
Fair market value generally reflects the price informed parties would accept without being forced to transact. Independent negotiations can provide evidence supporting that value. The Internal Revenue Service recognizes arm’s-length valuations as strong evidence of fair market value in appropriate circumstances.
That connection matters because prices affect taxes, financing, appraisals, and reported gains or losses. An artificially low or high price can distort those calculations. A documented market-based price makes the transaction easier to explain later.
Readers weighing a property deal between connected parties may also want the Artandwriters explainer on what a deed of trust is. It covers the parties involved, how a deed of trust differs from a mortgage, and the basics of foreclosure.
Arm’s Length vs. Non-Arm’s-Length Transactions
The easiest distinction involves the relationship between the parties and their incentives. Independent participants normally protect their separate financial interests. Related participants may have reasons to offer terms that an unrelated person would reject.
| Factor | Arm’s-Length Deal | Non-Arm’s-Length Deal |
|---|---|---|
| Relationship | Independent parties | Family, partners, affiliates, or connected parties |
| Negotiation | Separate interests | Interests may overlap |
| Pricing | Usually market-driven | May include discounts or unusual terms |
| Influence | No improper control | Influence may affect decisions |
| Scrutiny | Normal review | Often receives added lender or tax review |
| Valuation | Can support market value | May require extra valuation evidence |
A father selling a house to his child below its normal market value is a simple example. The relationship may explain the discounted price. That sale may still be legal, but it is not a typical independent-market transaction.
A sale between unrelated buyers and sellers can still raise concerns when one party controls the process. Undisclosed agreements can also weaken the appearance of independence. The facts matter more than the labels on the paperwork.
A Simple Arm’s Length Transaction Example
Imagine a homeowner lists a property for $400,000 through the open market. An unrelated buyer offers $380,000 after comparing nearby homes. The seller counters at $392,000, and both sides settle at $388,000.
Neither party has a prior relationship or hidden agreement. Each side receives professional advice and can walk away from the negotiation. Those facts strongly resemble normal independent bargaining.
The final price does not automatically become the property’s exact market value. Appraisers and lenders may still study comparable sales and market conditions. Still, the negotiation provides useful evidence because both parties pursued separate interests.
Readers considering a home sale can also review Artandwriters’ guide to options for selling a home. It provides additional context around selling methods and market-based negotiations.
Why Arm’s Length Transactions Matter in Real Estate
Real estate lenders and appraisers care about relationships because those relationships can affect sale prices. A family discount may make a property appear cheaper than comparable homes. A hidden incentive could push a price above normal market levels.
Federal housing guidance has historically treated independent transactions as important evidence when appraisers select comparable sales. Transactions involving foreclosures, estates, or other unusual circumstances can require additional analysis. The goal is to understand whether the price reflects normal market behavior.
Mortgage lenders may also ask whether buyers and sellers know each other. That question helps identify undisclosed concessions or conflicts of interest. Accurate disclosure protects the integrity of the financing process.
A related-party property sale is not automatically prohibited. Buyers should expect additional documentation when family members or business associates are involved. An independent appraisal and clear records can help explain how the parties reached the price.
What Does an Arm’s Length Transaction Mean for Taxes?
Tax authorities often care whether connected parties use prices that independent parties would accept. Artificial prices can shift income, gains, deductions, or asset values. That problem becomes especially important in business transactions between related entities.
For individuals, fair market value can matter when property is sold, exchanged, or transferred. The IRS defines fair market value using willing buyers and sellers with adequate knowledge. Neither party should face compulsion to complete the transaction.
A family sale below market value can create tax questions beyond the sales contract. Depending on the facts, part of the transfer could receive different tax treatment. U.S. taxpayers should seek qualified tax advice for substantial related-party transfers.
Businesses face another layer through transfer-pricing rules. Under Section 482 of the Internal Revenue Code, the IRS can reallocate income between commonly controlled businesses so the results match what unrelated parties would have agreed, as Treasury Regulation 1.482-1 at Cornell Law School’s Legal Information Institute explains. Documentation can become important when authorities review how prices were established.
How Can You Show That a Deal Was Negotiated Independently?
Good documentation can help demonstrate how parties reached their agreement. Records matter most when a relationship or unusual price might attract questions. They can also help lenders, accountants, attorneys, or tax professionals understand the deal.
Useful evidence can include the following items.
- Independent appraisals or valuations
- Comparable market sales
- Written offers and counteroffers
- Separate legal representation
- Broker or agent records
- Independent financing
- Inspection reports
- Negotiated contract terms
- Written disclosure of existing relationships
No single document proves every transaction is independent. The complete pattern of conduct carries more weight. Market exposure, negotiation history, and each party’s ability to refuse the deal can all matter.
Can Family Members Complete an Arm’s-Length Deal?
Family members can buy and sell property from each other, but their relationship changes the analysis. A transaction between relatives is commonly treated as a related-party deal. That means outsiders may not assume the price resulted from independent bargaining.
The parties can still use market evidence when setting their price. They might obtain an appraisal, review comparable sales, and use separate advisers. Those steps can support the reasonableness of the agreed value.
Calling a family transfer an arm’s length transaction does not make it one automatically. Lenders and tax professionals will examine the underlying relationship and terms. Full disclosure is safer than trying to make a connected transaction appear unrelated.
Common Warning Signs of a Non-Arm’s-Length Deal
Several features may suggest that normal market forces did not determine the terms. A close relationship is the most obvious signal. Unusual concessions or unexplained pricing can create similar concerns.
Watch for the following signs.
- Buyer and seller are close relatives.
- One party controls the other business.
- The property was never exposed to the market.
- The price differs sharply from comparable values.
- One side receives unusual credits or concessions.
- A hidden agreement changes the real economics.
- One party is under pressure from the other.
- The parties share advisers despite conflicting interests.
These factors do not always prove wrongdoing. They simply show that the deal may need more explanation. Independent professional advice can reduce uncertainty before closing.
When Should You Get Professional Advice?
Professional guidance makes sense when a deal involves family members, related companies, valuable property, or unusual pricing. A real estate attorney can review ownership and contract issues. A CPA or tax professional can address federal and state tax consequences.
An appraiser can help establish a supportable property value. Business valuation professionals can perform similar work for companies and intangible assets. Their reports may provide useful evidence when relationships make market value less obvious.
Do not assume a fair-looking price eliminates every legal or tax issue. Different rules can apply depending on the asset and transaction structure. State law can also affect property and contract questions.
The Bottom Line
Independent bargaining helps make prices and contract terms easier to evaluate. It can support fair market value and reduce questions about hidden influence. Clear records become especially valuable when property, taxes, or financing are involved.
Before completing a connected-party deal, disclose the relationship and document how the value was determined. Use independent advisers when the financial stakes are significant. That approach can prevent avoidable problems with lenders, appraisers, regulators, and tax authorities.
Frequently Asked Questions
What is an arm’s length transaction in simple terms?
An arm’s length transaction is a deal between independent parties acting for their separate interests. Neither side receives special treatment because of a personal relationship. The negotiation generally resembles what unrelated market participants would do.
What is the opposite of an arm’s-length deal?
The opposite is usually called a non-arm’s-length or related-party transaction. Examples include some deals between relatives, business partners, or affiliated companies. These transactions can be legitimate but often require closer review.
Does an arm’s-length sale always equal fair market value?
No. Independent bargaining can provide strong evidence of fair market value, but it does not guarantee a perfect valuation. Market conditions, financing terms, and unusual property features can still affect price.
Is a sale between family members illegal?
No. Family members can legally buy, sell, or transfer property to each other. Tax, lending, and valuation rules may require additional documentation or disclosure.
Why do mortgage lenders ask about the relationship between buyer and seller?
Lenders want to know whether a relationship could affect the purchase price or concessions. Connected parties may negotiate terms differently from unrelated buyers and sellers. Disclosure lets the lender assess the transaction accurately.
Are related-company transactions subject to the same principle?
Yes, the independence principle is important in U.S. transfer pricing. Related companies may need to support prices using terms comparable to independent transactions. Large or complex arrangements often require specialized tax advice.